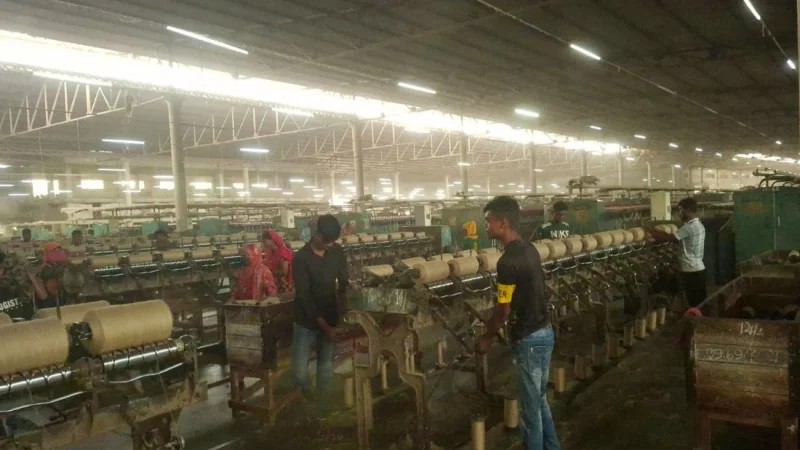
Super Jute Mill, once one of Bangladesh’s leading private-sector exporters of jute products, is struggling under mounting debt, raising fears of bankruptcy. The mill, which once earned Tk20-30 lakh a day and exported products to 24 countries, has seen its fortunes reverse amid a prolonged financing crisis. Superex Leather, another company owned by the same entrepreneur, is also facing severe financial difficulties.
Entrepreneur M Firoz Ahmed Bhuiyan has blamed the downturn on a lack of bank financing. In contrast, Islami Bank Bangladesh PLC states that the company has failed to present a specific loan repayment plan and repay installments.
Established in 2006 at Alka village of Phultala upazila with an investment of around Tk250 crore, Super Jute Mill employed nearly 5,000 people and received state awards three times for its export contributions. Following its success, Bhuiyan invested around Tk700 crore in 2016 to establish Superex Leather in Khulna, installing advanced machinery, obtaining Leather Working Group certification, and setting up an Italian effluent treatment plant.
However, a shortage of working capital hampered operations. The company purchased leather worth around Tk150 crore using its own funds but failed to secure bank financing for processing chemicals, causing leather values to drop significantly. Bhuiyan stated that production contracted after the bank stopped providing necessary working capital after 2017, alleging that previous bank controllers withheld financing to weaken his businesses.
Superex Leather was once valued at around Tk700 crore against bank liabilities of approximately Tk600 crore, with total outstanding debt now rising to around Tk900 crore including principal and interest. Bhuiyan noted the factories could resume production if provided with about Tk200 crore in working capital support.
Islami Bank’s Daulatpur branch manager Iftekhar Hossain said the company had not submitted a specific loan repayment plan. He added that the firm had failed to utilize an opportunity under a special Bangladesh Bank circular to regularize defaulted loans by depositing 2% of the outstanding amount.
Why it matters
The financial distress of major industrial enterprises in Khulna highlights critical lending challenges and banking sector disputes affecting key private-sector exports and employment in Bangladesh.